How Much Is Your Home Worth?
- Instant property valuation
- Expert advice
Loading valuation...
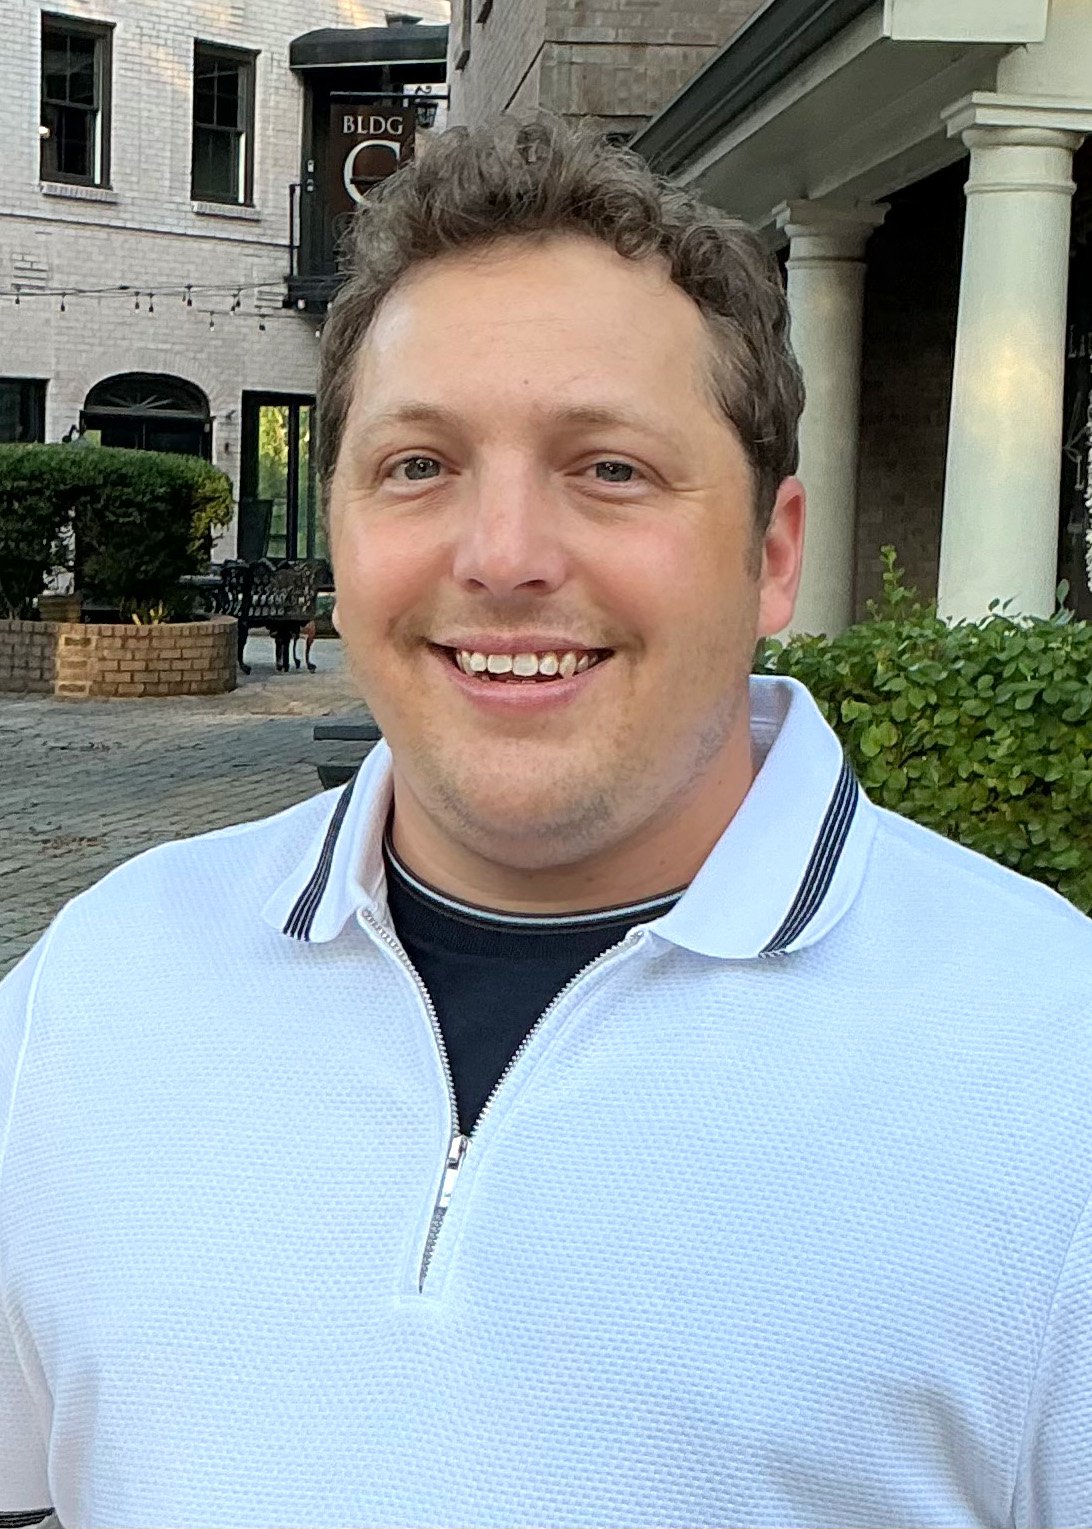
Originally from Louisville, Kentucky, Brent Brown has called Middle Tennessee home for over a decade. After spending a year in Williamsport, and four years in Brentwood, he has now been nestled in the heart of downtown Franklin for several years where he has built deep roots through his church, ministry involvement, and dedication to the local community.
Before entering real estate, Brent spent four years with a public water utility serving the Franklin and Brentwood areas, and six years in residential electrical work throughout Middle Tennessee. This hands-on experience shaped his practical, detail-oriented approach and taught him the importance of being dependable, prepared, and attentive to the needs of others. Today, Brent brings that same mindset into real estate.
With a strong desire to help others, Brent felt called to real estate. He strives to be responsive, honest, thorough, and prepared while taking a genuine personal interest in every client he serves. Whether buying or selling, he takes the time to understand each client’s individual goals, wants, and needs, providing thoughtful guidance and a client-centered experience from start to finish. For Brent, Real Estate is about more than a transaction—it’s about helping people feel seen, heard, and confident in one of the most important decisions they will make.
Outside of real estate, Brent is grateful to share life with his wife, Stephanie, an elementary school teacher in the local area. Together, they enjoy actively serving the Middle Tennessee community they are proud to call home.
Not necessarily. Many homeowners coordinate the sale of their current home with the purchase of their next one, often using the proceeds from the sale toward the next purchase. This can sometimes be done through a sale contingency or bridge financing, allowing you to purchase before your current home sells. The timing of the two transactions can often be coordinated to help make the transition from one home to the next smoother. Speaking with your agent about your finances, timing, and goals can give you a better idea of which options may be available to you.
You don't need to be pre-approved to start looking at homes. However a "Pre-qualification" is a brief estimate from a lender that can help you understand your potential price range and can be a helpful first step. A "Pre-approval" involves a more thorough review of your financial information and is typically the next step when you're ready to move forward with purchasing a home.
No, 20% down is not required for many home loans. There are actually a wide range of loan programs designed for different financial situations and types of buyers, with different minimum down-payment requirements. Putting 20% down is one option, with one benefit being that it can help lower your monthly payment, but many buyers qualify for a loan that requires considerably less.
There are several factors to consider when deciding whether to buy now or wait for rates to change. The market value of homes changes over time, so waiting for a lower interest rate doesn't necessarily mean you'll save money-in fact, you could end up paying more. The value of the home and the terms of the loan can both affect how much you pay, not just the interest rate. There are also actually options that may help lower your rate, such as buying discount points, which can sometimes be negotiated with the seller as part of the purchase. As well when rates drop after you buy, refinancing your mortgage can be an option, allowing you to take advantage of the lower rate
A home inspection looks at the condition of the home, including its components, and major systems to ensure whether they are in proper working order. An appraisal determines the home’s value based on factors such as the property, its condition, and comparable homes in the area. In simple terms, an "inspection" is about the "condition" of the home, while an "appraisal" is about its "value"
"Homeowners insurance" is a policy that can protect your home and belongings against certain risks, such as theft or water damage. "Hazard insurance" is a part of that policy that covers certain physical risks to the home, such as fire or severe weather. A "Home warranty" is different and typically covers the repair or replacement of certain home systems and appliances when they break down.
"Earnest money" is a deposit made by the buyer to show the seller that they are serious about purchasing the home. It helps "put the home on hold" while the buyer and seller work through the purchase, with the signed contract. The money is typically held in an "escrow" account and, if the purchase is completed, is generally applied toward the down payment. Depending on the terms of the contract, the buyer may be able to receive the deposit back if the transaction does not move forward.
Closing costs are the fees and adjustments involved in completing a real estate transaction. They can include expenses related to the loan, title, insurance, and taxes, as well as prorated expenses between the buyer and seller, so each party pays their share based on how long they own the property.
Enter your details to see how much your home is worth.
Schedule a free consultation with Brent a local agent who can help you estimate and understand your home's potential value.
Brent Brown
Realtor
We need more information to provide an accurate estimate for this address. Local expert Brent Brown will reach out shortly or you can schedule a consultation now.